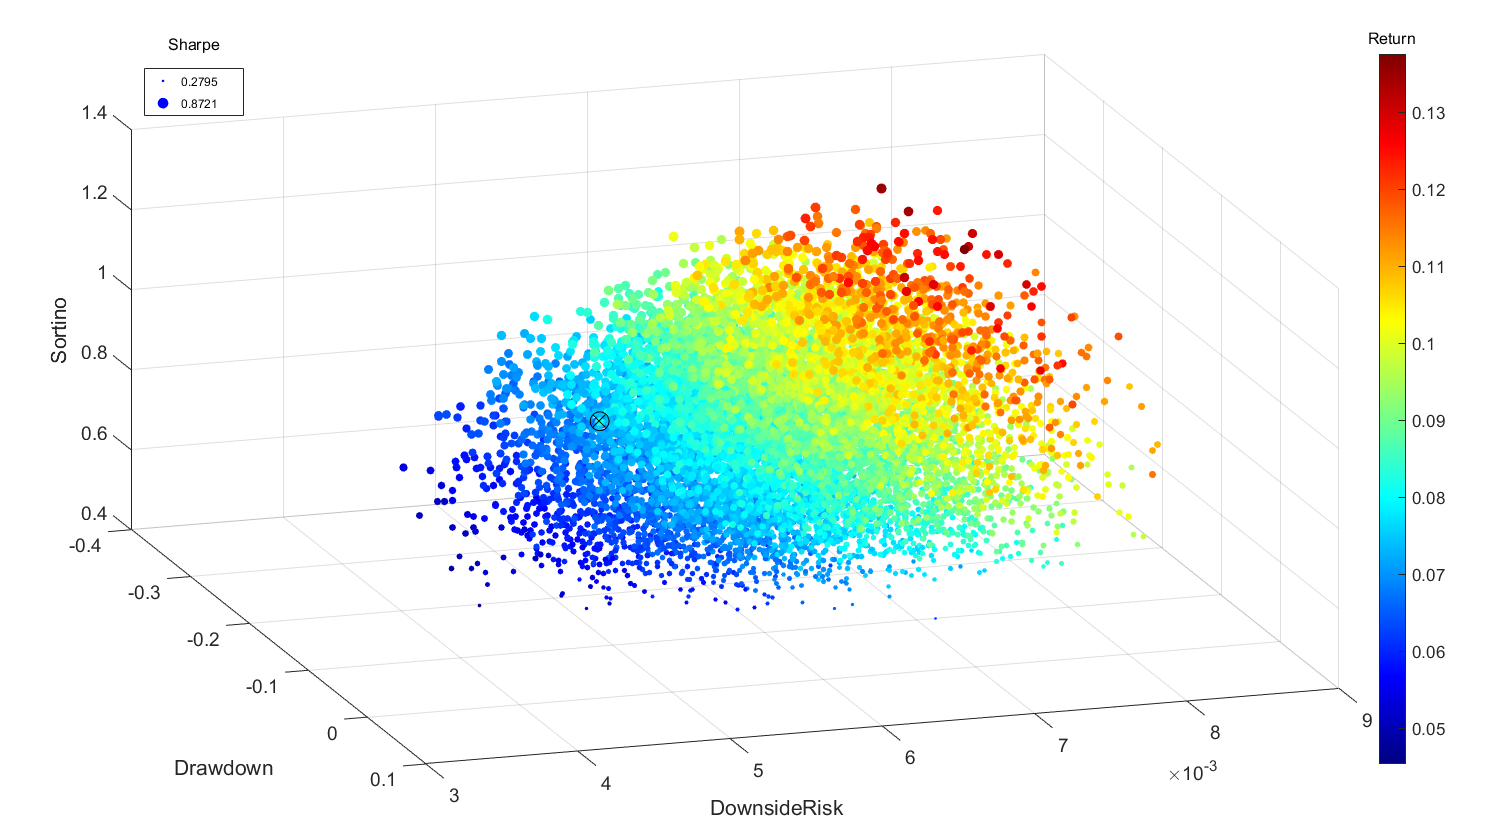
portfolio_sortino_ratio
Optimize portfolio weights for a weighted linear combination of Sortino ratio, Sharpe ratio, total return, downside risk, SD, & max drawdown

You are now following this Submission
- You will see updates in your followed content feed
- You may receive emails, depending on your communication preferences
Cite As
Elliot Layden (2026). portfolio_sortino_ratio (https://github.com/elayden/portfolio_sortino_ratio), GitHub. Retrieved .
Acknowledgements
Inspired by: Click3dPoint, Random Vectors with Fixed Sum
General Information
- Version 1.0.1 (834 KB)
-
 View License on GitHub
MATLAB Release Compatibility
- Compatible with R2014b and later releases
Platform Compatibility
- Windows
- macOS
- Linux
| Version | Published | Release Notes | Action |
|---|---|---|---|
| 1.0.1 | -added photo |
To view or report issues in this GitHub add-on, visit the GitHub Repository.
To view or report issues in this GitHub add-on, visit the GitHub Repository.

