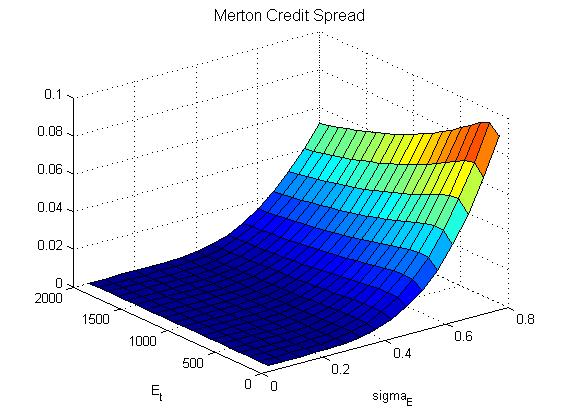
Merton Structural Credit Model (Matrixwise Solver)
Matrixwise Calculation Firm Asset Value, Volatility, Debt Value, Spread, Default Prob, Exp-Recovery

You are now following this Submission
- You will see updates in your followed content feed
- You may receive emails, depending on your communication preferences
Cite As
Mark Whirdy (2026). Merton Structural Credit Model (Matrixwise Solver) (https://www.mathworks.com/matlabcentral/fileexchange/39717-merton-structural-credit-model-matrixwise-solver), MATLAB Central File Exchange. Retrieved .
Acknowledgements
Inspired by: MTIMESX - Fast Matrix Multiply with Multi-Dimensional Support
General Information
- Version 1.5.0 (2.87 KB)
MATLAB Release Compatibility
- Compatible with any release
Platform Compatibility
- Windows
- macOS
- Linux
| Version | Published | Release Notes | Action |
|---|---|---|---|
| 1.5.0 | Removed fsolve dependency (Optim Toolbox) for efficiency increase (even in scalar inputs case) Full Code re-factorization to facilitate matrixwise calculation of bivariate ranges of {E_t,sig_E,K,T} values using 3d Newton Jacobian solution. |
||
| 1.4.0 | Added the Black-Scholes Parameter Anonymous Function Handle as an Output to allow for further analysis (sensitivity, greeks etc) d = @(z,A_t,sig_A,T,t,K,r)((1/(sig_A*sqrt(T-t)))*(log(A_t/K) + (r + (z)*0.5*sig_A^2)*(T-t))); z = +1/-1 |
||
| 1.3.0 | Minor code refactoring, code returns the Black-Scholes Parameter to allow for further sensitivity analysis & calculation of greeks d = @(z,A_t,sig_A,T,t,K,r)
|
||
| 1.1.0 | Added Expected-Recovery calclulation [A_t,sig_A,D_t,s,p,R] = calcMertonModel(E_t,sig_E,K,t,T,r); |
||
| 1.0.0 |

